Unlocking Short-Term Mortgage Solutions to Monetise Your Assets
Explore how short-term mortgage solutions can help you monetise your assets without cashing them in. Understand how leveraging investment portfolios and pension pots can support borrowing needs.
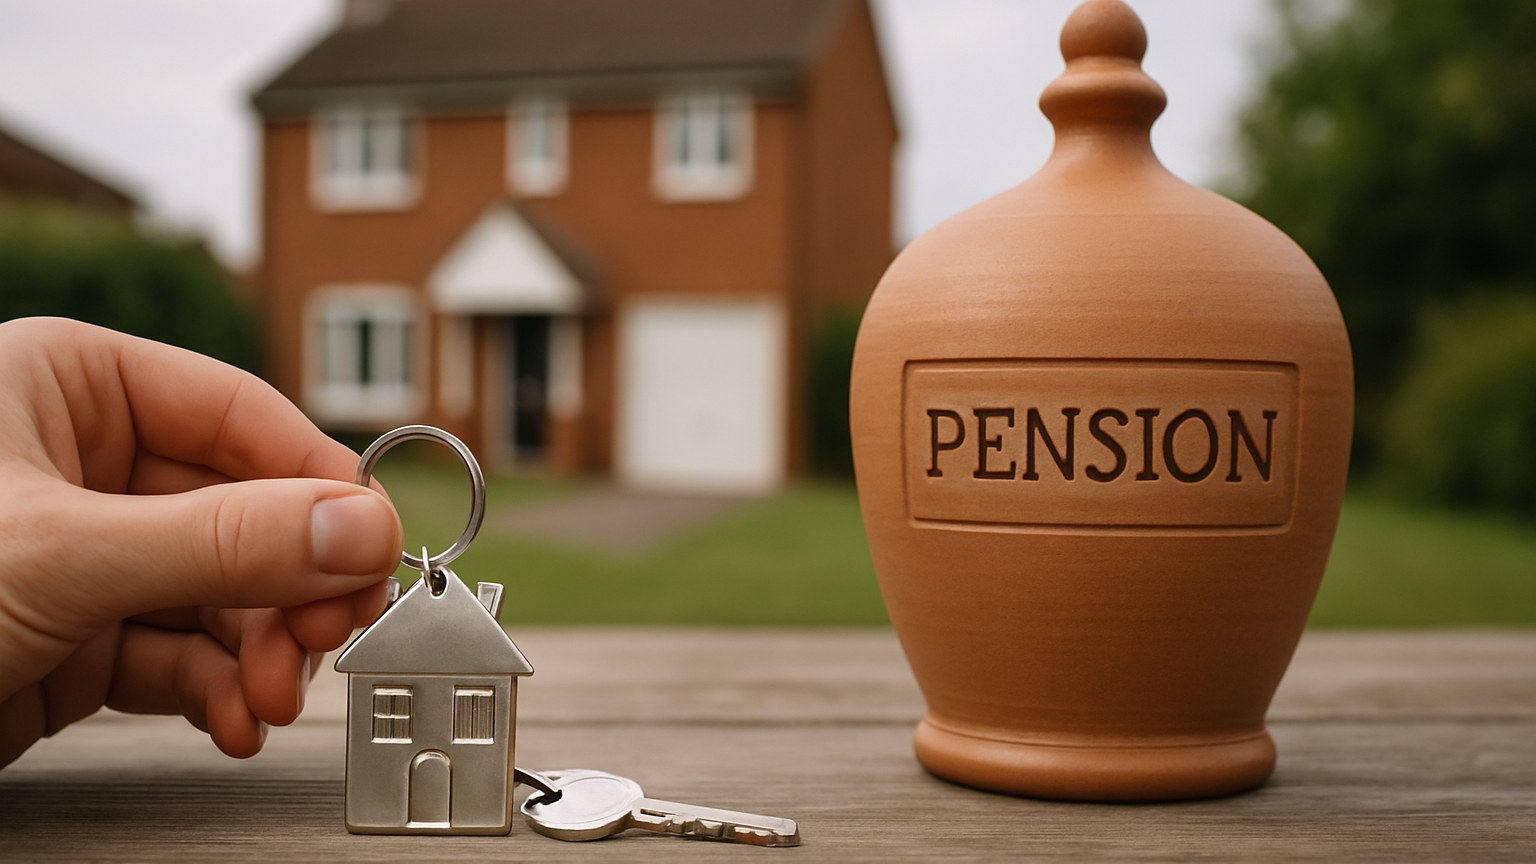
When faced with the need to quickly turn assets into cash flow, especially for property transactions, a short-term mortgage solution might be just the ticket. Such options can offer flexibility, leveraging assets like pensions and investment portfolios rather than liquidating them.
What is a Short-Term Mortgage Solution?
A short-term mortgage solution allows homeowners to access funds for a limited period without the need to permanently restructure their financial holdings. It's an opportunity for those with substantial, but less liquid, assets.
How Does it Work?
- Leveraging Liquid Assets: Rather than selling your investments, such as managed portfolios or your pension pot, these assets can ‘stand behind’ your loan, showing the lender that you have the resources to cover the repayments, even if you're not drawing from these funds directly.
- Interest-Only Lending: Many lenders offer interest-only mortgage products under these circumstances, allowing for lower monthly payments throughout the term. However, you'll need a clear repayment strategy by the end of the term.
Example Scenario
Consider a couple in their late 70s planning to downsize. They're selling a £1.2m property to buy a new home worth £850k. With a significant pension and ISA investments, they can access a short-term mortgage, using these assets as leverage. This allows them to buy the new home without rushing the sale of their existing house.
Benefits and Risks
- Flexible Funding: Access to large sums without liquidating assets. However, this requires evidence of a suitable repayment strategy.
- Repayment Plans are Crucial: As these loans are often interest-only, make sure you can repay the principal.
Is This Right for You?
While a short-term mortgage provides plenty of flexibility, it's crucial to assess your financial situation carefully. Factors like the potential for asset value fluctuation or changes in repayment capacity should be considered.
For those thinking about taking this path, speaking with a financial advisor is a great next step. They'll help tailor the solution to your specific circumstances and ensure all aspects, including potential risks and repayment strategies, are thoroughly evaluated.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Verified Claims & Sources
-
•
"Short-term mortgage solutions can leverage assets like managed investment portfolios or pension pots without cashing them in." (Source #25)
-
•
"Interest-only loans up to 80% LTV are available with repayment strategies required." (Source #25)
Found this insight helpful?
Share it with your colleagues, network, or clients.
Subscribe to Anderson Reed Insights
Get expert financial guidance, mortgage rate updates, and property market analysis delivered straight to your inbox.
Speak to an Independent Mortgage Specialist
At Anderson Reed Financial Services, our qualified advisers provide impartial, whole-of-market mortgage and protection advice tailored to your personal circumstances across the UK.