Supporting Students onto the Property Ladder: 100% LTV Mortgages via Joint Borrower Sole Proprietor Arrangements
Joint Borrower Sole Proprietor (JBSP) mortgages can help students acquire property during their studies. Discover how parents can support their children's homeownership dreams with this innovative solution.
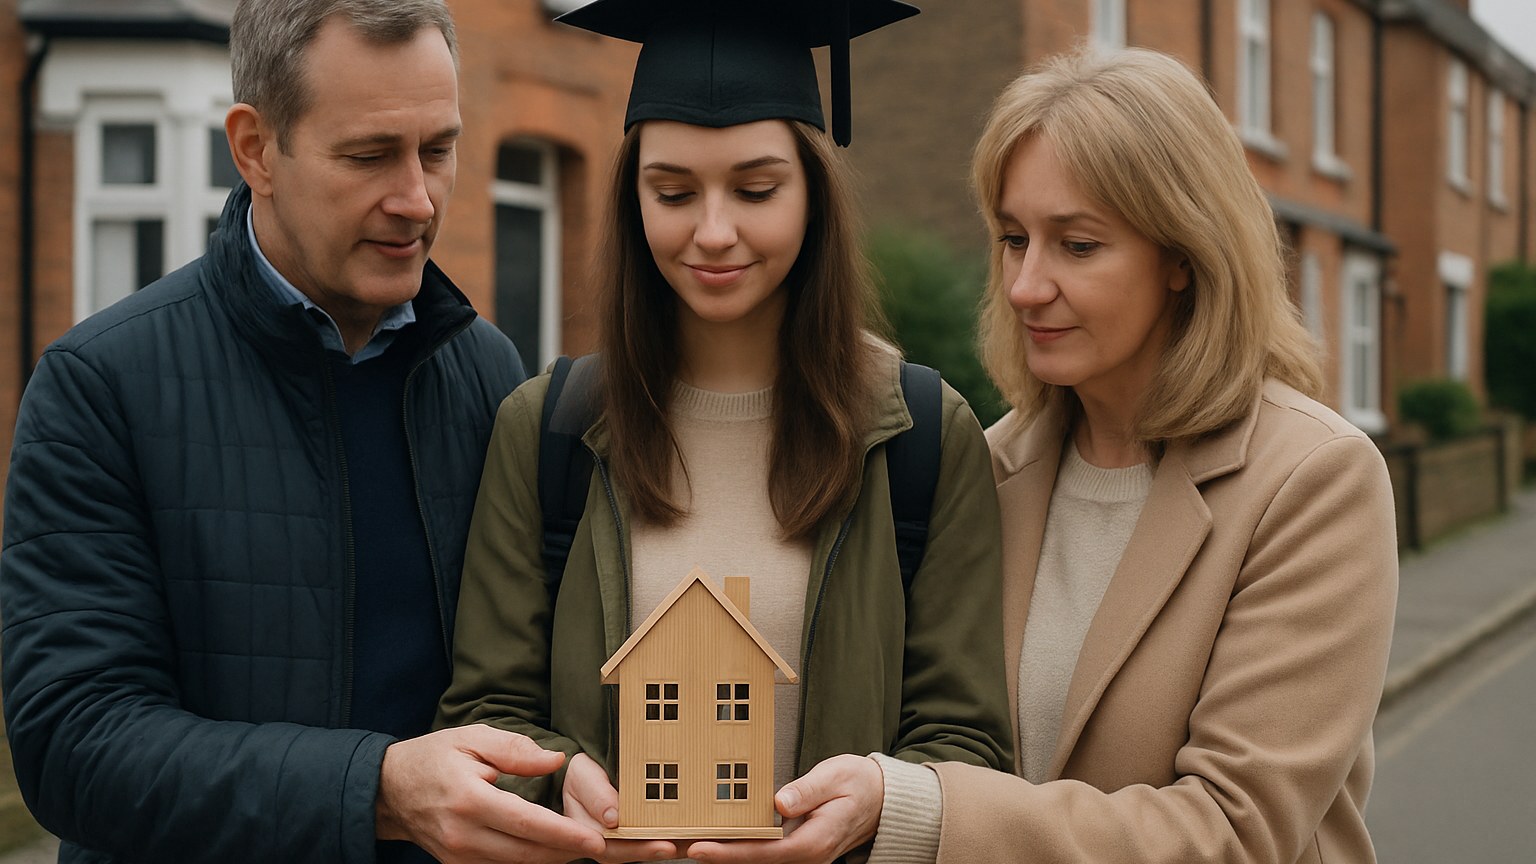
Buying a home while at university might seem like a distant dream for many students, especially without a deposit or consistent income. However, the Joint Borrower Sole Proprietor (JBSP) mortgage can be a viable option, supported by the income of parents looking to invest in their child's future. Here's a closer look at how this mortgage works and what you need to consider.
What is a JBSP Mortgage?
A JBSP mortgage allows parents or family members to help their children get onto the property ladder without being a co-owner of the property. This means that while the mortgage is supported by the income of the parents, the property is owned solely by the student.
The Scenario
Consider Sarah, an 18-year-old student with a strong potential for future earnings, planning to start her university journey. Renting during her studies seems costly, and owning a home near the university appears more attractive. But without an income or deposit, the path to homeownership is challenging.
Sarah’s parents, with a combined income of £85,000, want to support her by purchasing a property worth £250,000 using a JBSP mortgage at 100% Loan-to-Value (LTV).
How It Works
- Income Support: The JBSP allows parents to use their income to assess mortgage affordability while the property remains solely in the student's name.
- No Deposit Needed: Students like Sarah can secure property ownership without the need for an upfront deposit, relying instead on the supporting borrowers’ financial stability.
- Long-term Benefits: As a capital repayment mortgage, this arrangement not only aids in securing accommodation during university but can also be a long-term investment as the student establishes their career.
Considerations and Risks
- Repayment Responsibility: Parents and children must understand that all borrowers are responsible for the entire mortgage debt. If repayments are not maintained, the property is at risk of repossession.
- Independent Legal Advice: It’s crucial for all involved parties to seek independent legal advice to fully understand their commitments and the implications of such arrangements.
Your home may be repossessed if you do not keep up repayments on your mortgage. Lending is always subject to an affordability assessment by the lender.
Is It Right for You?
A JBSP mortgage can be an attractive way to facilitate homeownership for students while leveraging parental support. It’s essential to thoroughly understand all responsibility aspects and engage in a careful consideration of personal and financial situations.
If you're contemplating this route, consulting with a mortgage advisor can provide tailored guidance to ensure the right decision for your family's circumstances.
Verified Claims & Sources
-
•
"A Joint Borrower Sole Proprietor (JBSP) mortgage involves parents supporting the mortgage without being co-owners of the property." (Source #18)
-
•
"Sarah, an example student, plans to purchase a property valued at £250,000 using a JBSP mortgage with her parents’ financial backing." (Source #18)
Found this insight helpful?
Share it with your colleagues, network, or clients.
Subscribe to Anderson Reed Insights
Get expert financial guidance, mortgage rate updates, and property market analysis delivered straight to your inbox.
Speak to an Independent Mortgage Specialist
At Anderson Reed Financial Services, our qualified advisers provide impartial, whole-of-market mortgage and protection advice tailored to your personal circumstances across the UK.