Understanding Why First-Time Buyers Often Face Higher Mortgage Costs Than Rent
More than half of former tenants who have transitioned to homeownership now face higher mortgage payments than their previous rent. Understanding the dynamics of this shift can help you navigate your path to buying a home.
First-Time Buyers Face Rising Costs
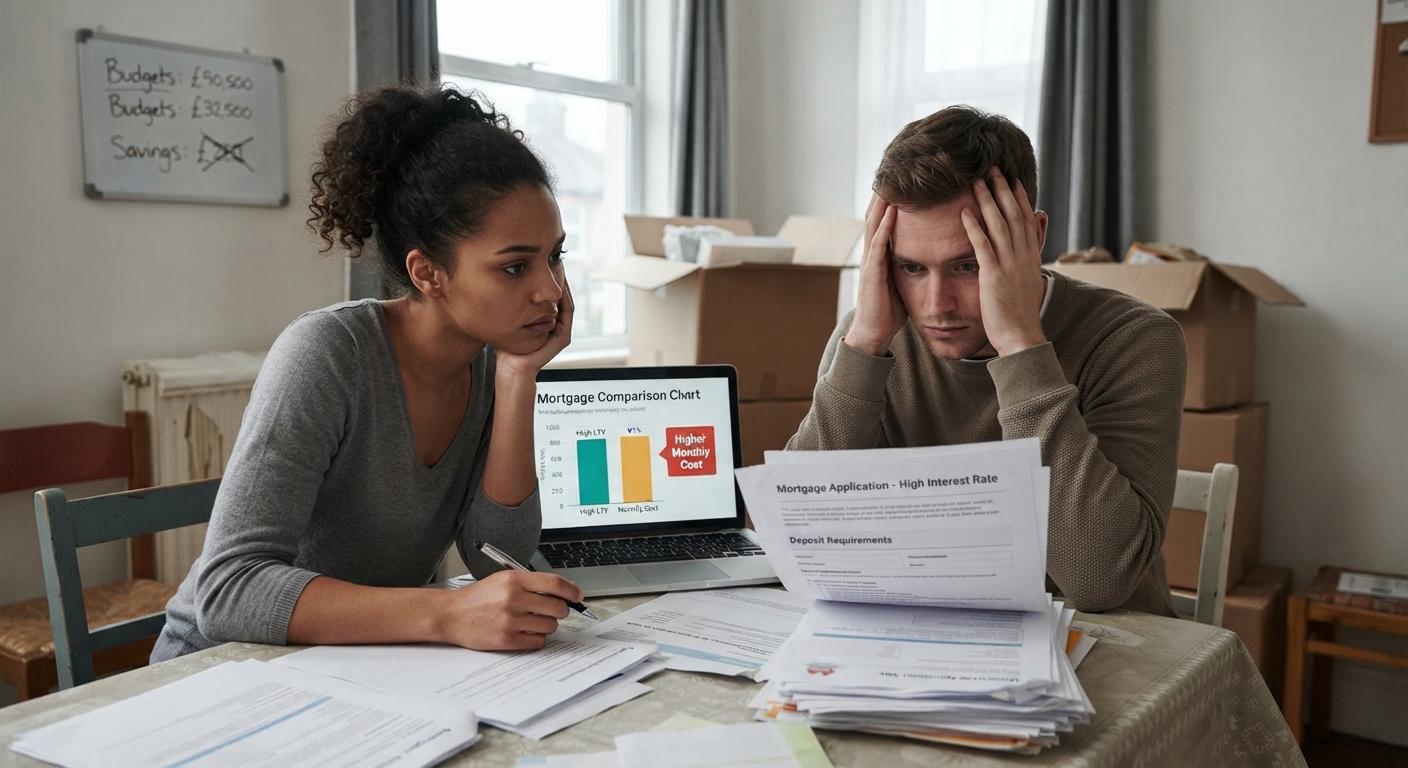
More than half of former renters (56%) now pay more for their mortgage than they did for rent. This marks a significant shift from earlier this year, when buying a home typically lowered monthly housing expenses.
What is Driving the Shift?
- High Loan-to-Value (LTV) Ratios:
- Buyers paying more than their previous rent average a 91% LTV.
- Smaller deposits result in larger loan sizes and higher monthly payments.
- Macroeconomic Pressures:
- Elevated interest rates are squeezing borrowing capacity and affordability.
- Demographic Choices:
- Older first-time buyers frequently purchase larger properties.
- They often opt for shorter mortgage terms, accelerating monthly repayment costs.
Regional and Demographic Insights
| Age Group | Average Cost Change vs. Rent | Average Mortgage Term |
|---|---|---|
| 20s | -7.5% (Paying less) | 34 years |
| 30s | +7.0% (Paying more) | ~31 years |
| 40s | +18.0% (Paying more) | 27 years |
The Long-Term Outlook
While initial monthly outgoings may be higher, homeownership continues to offer core wealth-building mechanisms that renting cannot match:
- Equity Accumulation: Monthly payments actively reduce principal debt rather than paying a landlord.
- Asset Security: Elimination of landlord-driven evictions or unpredictable rental hikes.
- Rental Market Context: Renting is not a static cost; average UK rents have risen 2.7% year-over-year.
Actionable Strategies for Buyers
To mitigate high initial monthly costs, consider the following structural adjustments:
- Target Lower LTV Thresholds: Injecting a larger deposit reduces the risk premium charged by lenders.
- Extend the Mortgage Horizon: Opting for a longer term lowers immediate monthly outgoings, though it increases total interest paid over the life of the loan.
- Overpayment Privileges: Utilise lender overpayment allowances (typically up to 10% per year) to chip away at principal early without contractual pressure.
For personalised guidance tailored to your specific financial circumstances, Anderson Reed is here to help.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Verified Claims & Sources
-
•
"56% of first-time buyers are paying more on their mortgages than previous rent." (Source #33)
-
•
"First-time buyers in their 40s see an average 18% increase in housing costs." (Source #33)
-
•
"Rent prices have increased by 2.7% year-on-year across Britain." (Source #33)
Found this insight helpful?
Share it with your colleagues, network, or clients.
Subscribe to Anderson Reed Insights
Get expert financial guidance, mortgage rate updates, and property market analysis delivered straight to your inbox.
Speak to an Independent Mortgage Specialist
At Anderson Reed Financial Services, our qualified advisers provide impartial, whole-of-market mortgage and protection advice tailored to your personal circumstances across the UK.