Managing Climate and Weather Risks: Impact on UK Property and Mortgage Eligibility
Evolving weather patterns and heightened environmental risks are transforming how UK mortgage lenders evaluate property suitability. Understanding your obligations regarding buildings insurance and environmental due diligence is essential for protecting your property assets.
How Flood Risk, Coastal Erosion and Changing Weather Can Affect Your Mortgage
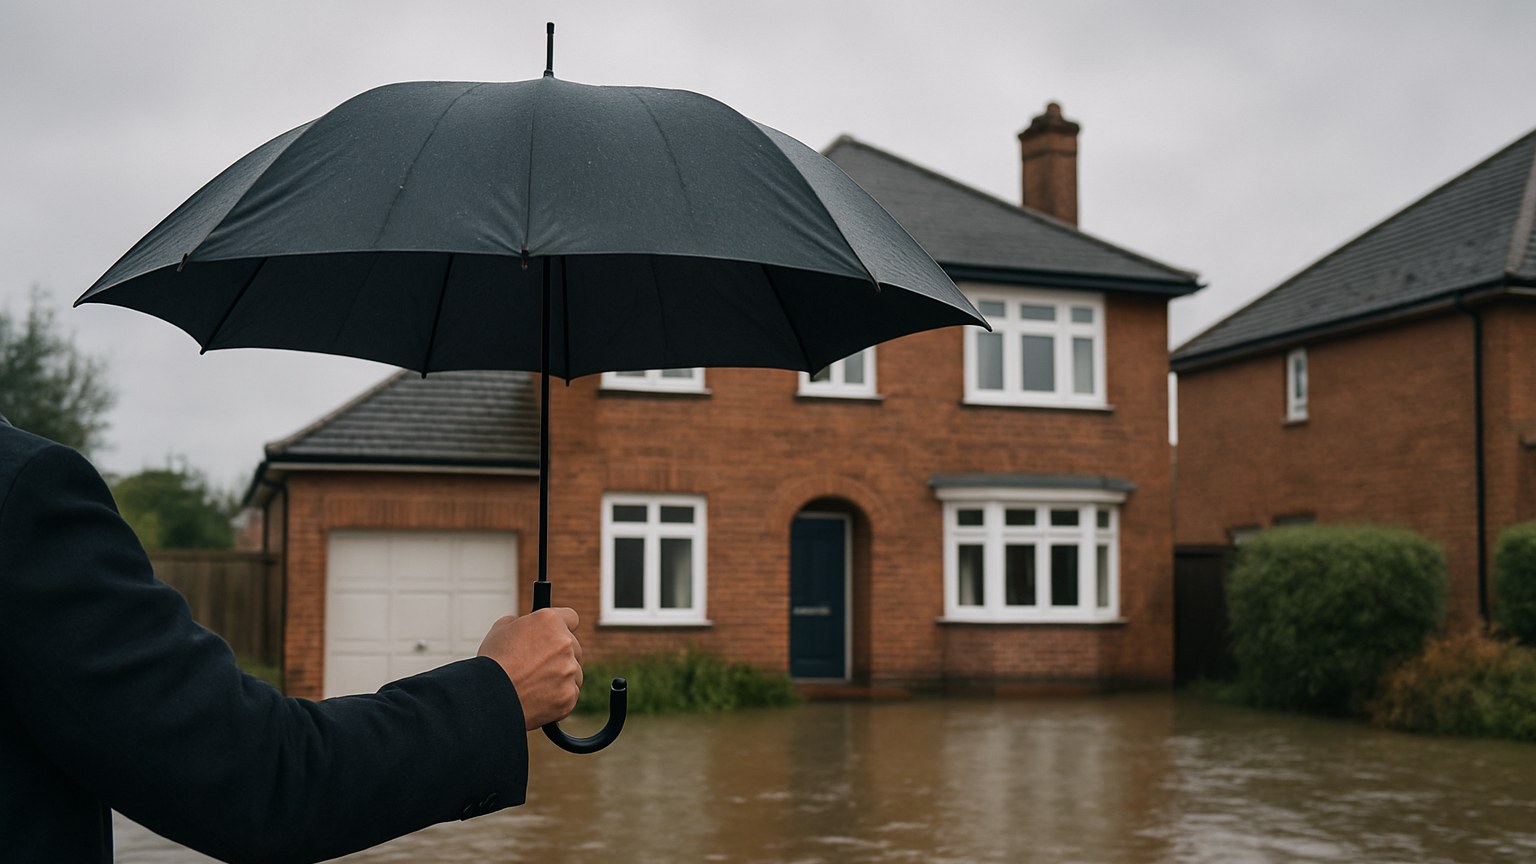
Changing weather patterns, coastal erosion and more frequent flooding are affecting how lenders and insurers assess residential property across the UK.
For homeowners and prospective buyers, environmental risks can influence whether a property is suitable for a mortgage, the availability and cost of buildings insurance, and how easy it may be to remortgage or sell in the future.
Buildings Insurance and Your Mortgage
Buildings insurance is normally a condition of a residential mortgage. The cover should be sufficient to meet the full cost of rebuilding the property—not simply its current market value.
For leasehold properties, buildings insurance may be arranged by the freeholder or managing agent, with the cost included within the service charge. Your solicitor or conveyancer should confirm the arrangements that apply to the property.
When considering the overall cost of owning a home, it is important to look beyond the monthly mortgage payment. Your budget may also need to cover:
- Buildings and contents insurance
- Council Tax, or domestic rates in Northern Ireland
- Ongoing maintenance and repairs
- Leasehold service charges and ground rent, where applicable
- Costs associated with protecting the property from flooding or other environmental risks
Your home may be repossessed if you do not keep up repayments on your mortgage.
Understanding Environmental and Flood Risk
Lenders, valuers, insurers and conveyancers may consider environmental risks when assessing a property.
Homes affected by coastal erosion or at significant risk from rivers, the sea, surface water or groundwater may require further investigation. Depending on the circumstances, a lender may request additional reports, impose particular conditions or decide that the property falls outside its lending criteria.
Important areas to investigate include:
Official Flood-Risk Information
Buyers and homeowners can use government-backed services to investigate the long-term flood risk for a particular area.
Different services apply across England, Scotland, Wales and Northern Ireland. In England, the official GOV.UK service provides information about potential flooding from rivers, the sea, surface water, reservoirs and groundwater where data is available.
Check the long-term flood risk for an area in England
Conveyancing Searches
Your solicitor or conveyancer will usually carry out searches relevant to the property and its location.
These may identify previous flooding or potential risks associated with flooding, land contamination, ground stability and other environmental concerns. Additional specialist reports may be recommended where a search identifies a possible problem.
Buildings Insurance
Insurance policies can differ considerably, so it is important to check:
- Whether flood and storm damage are covered
- The amount of any flood-related excess
- Whether particular conditions or exclusions apply
- Whether previous flooding must be disclosed
- Whether suitable cover will remain affordable
A property with an attractive purchase price may not necessarily represent good value if it is difficult or expensive to insure, mortgage or sell in the future.
Considering a home in a coastal or flood-risk area?
Speak to Nigel or the Anderson Reed team before committing yourself. We can explore the mortgage options available and help identify potential lender concerns at an early stage.
Finding Insurance for Higher-Risk Properties
Properties in areas with a history of flooding can sometimes be more difficult or expensive to insure. However, specialist support may be available.
Flood Re
Flood Re is a joint initiative between the UK Government and the insurance industry. It is designed to help participating insurers provide more affordable flood cover for eligible homes.
Eligibility conditions apply, and Flood Re does not cover every property, type of ownership or occupancy. Your insurer should be able to confirm whether a property may qualify.
Specialist Insurance Brokers
A broker experienced in flood, coastal or other non-standard property risks may be able to approach specialist insurers that are not available through mainstream comparison websites.
Independent Support
The National Flood Forum provides support and guidance to people affected by flooding. MoneyHelper and Citizens Advice can also provide impartial information about household budgeting and insurance matters.
Protecting Your Property for the Future
Environmental risks and property values can change over time, so insurance and protective measures should be reviewed regularly.
Practical steps may include:
- Checking that your buildings insurance reflects the current rebuild cost
- Reviewing flood and coastal-erosion information for your area
- Keeping gutters, drains and watercourses properly maintained
- Investigating suitable flood-resilience measures
- Retaining records of improvements and professional assessments
- Checking with your insurer before making significant alterations
- Reviewing your insurance when circumstances change
Taking these steps can help protect your home, maintain suitable insurance and reduce potential difficulties when remortgaging or selling.
Speak to Us About Your Mortgage Options
Environmental risks do not automatically mean that a property cannot be mortgaged.
Different lenders have different criteria, and the most suitable approach will depend on the property, its location, the available insurance and your individual circumstances.
If you are buying, moving home or remortgaging a property in a coastal or flood-risk area, contact Nigel or the Anderson Reed team before committing yourself. We can discuss the property with you, explore suitable mortgage options and help you understand any potential issues.
Speak to Nigel
Nigel Kent CeMAP
Mortgage Adviser
Anderson Reed Financial Services Ltd
Call or WhatsApp: 07385 889288
Email: nigel@andersonreed.co.uk
Message Nigel on WhatsApp | Email Nigel
Speak to Anderson Reed Financial Services
Prefer to speak to the main Anderson Reed team? Contact us directly and one of our advisers will be happy to help.
Telephone: 02382 127779
Email: info@andersonreed.co.uk
Call Anderson Reed | Email Anderson Reed
No question is too small. Contact Nigel directly or speak to the Anderson Reed team to discuss your mortgage options.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Verified Claims & Sources
-
•
"Buildings insurance covering the full rebuild cost of the property is a standard mortgage requirement." (Source #19)
-
•
"Property owners can inspect long-term flood risk via GOV.UK tools." (Source #19)
-
•
"Flood Re acts as a resource to assist property owners who experience difficulties securing affordable flood insurance." (Source #19)
-
•
"Organizations such as the National Flood Forum and MoneyHelper provide guidance on flood risk and insurance difficulties." (Source #19)
Found this insight helpful?
Share it with your colleagues, network, or clients.
Subscribe to Anderson Reed Insights
Get expert financial guidance, mortgage rate updates, and property market analysis delivered straight to your inbox.
Speak to an Independent Mortgage Specialist
At Anderson Reed Financial Services, our qualified advisers provide impartial, whole-of-market mortgage and protection advice tailored to your personal circumstances across the UK.